

GST Update
Desk of CA. Praveen Sharma – 1063 Series (CAPS)
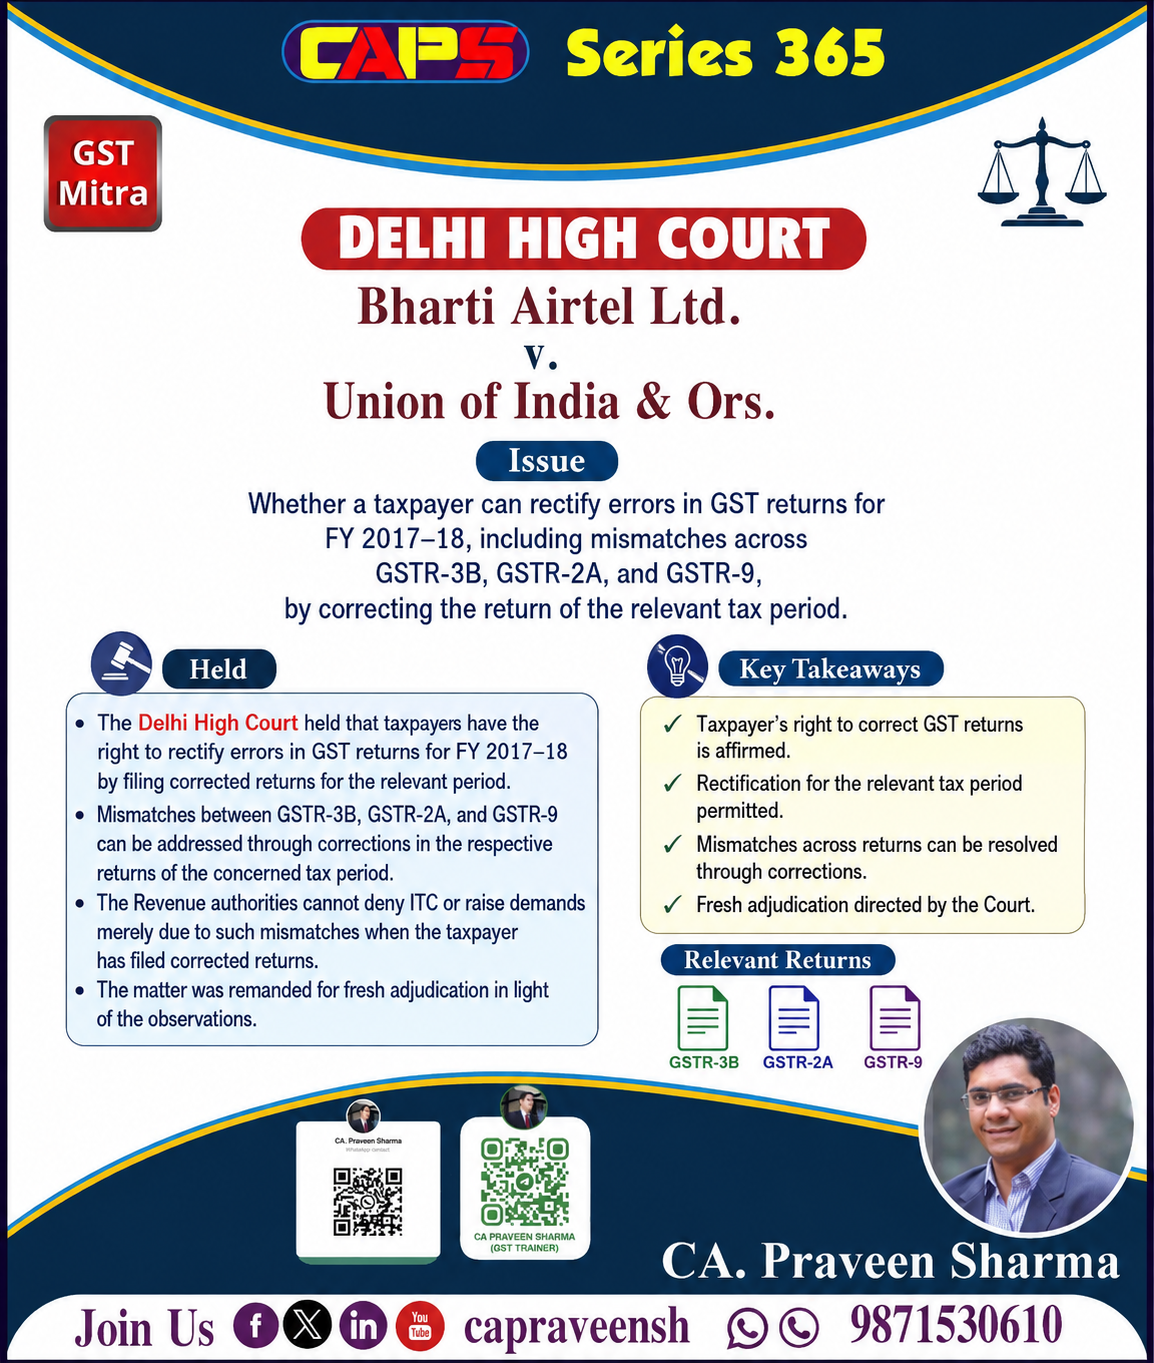
Delhi High Court – Bharti Airtel Ltd. v. Union of India & Ors.
The Delhi High Court held that genuine errors in GST returns for FY 2017–18 should be allowed to be corrected so that the correct tax liability is reflected. The case involved Bharti Airtel Ltd., which sought rectification of mistakes in GSTR-3B that had led to incorrect reporting of Input Tax Credit (ITC).
The Court observed that GSTR-3B is a statutory return under Section 39 of the CGST Act, and taxpayers cannot be denied the opportunity to correct bona fide mistakes merely because of procedural restrictions contained in a departmental circular. It further held that such corrections should relate back to the relevant tax period in which the error occurred and not be adjusted in a later return.
The Court directed the GST authorities to verify the corrected returns and give effect to the rectification in accordance with law. It emphasized that procedural technicalities should not override substantive tax rights, particularly where the taxpayer has acted bona fide and no revenue loss is caused.
The judgment provides significant relief to taxpayers facing genuine mismatches in GSTR-3B, GSTR-2A, and GSTR-9, reinforcing that the objective of GST is to determine the correct tax liability rather than penalise inadvertent reporting errors.
LINK: CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: