

GST Update
???? Desk of CA. Praveen Sharma – 1133 Series (CAPS) ????
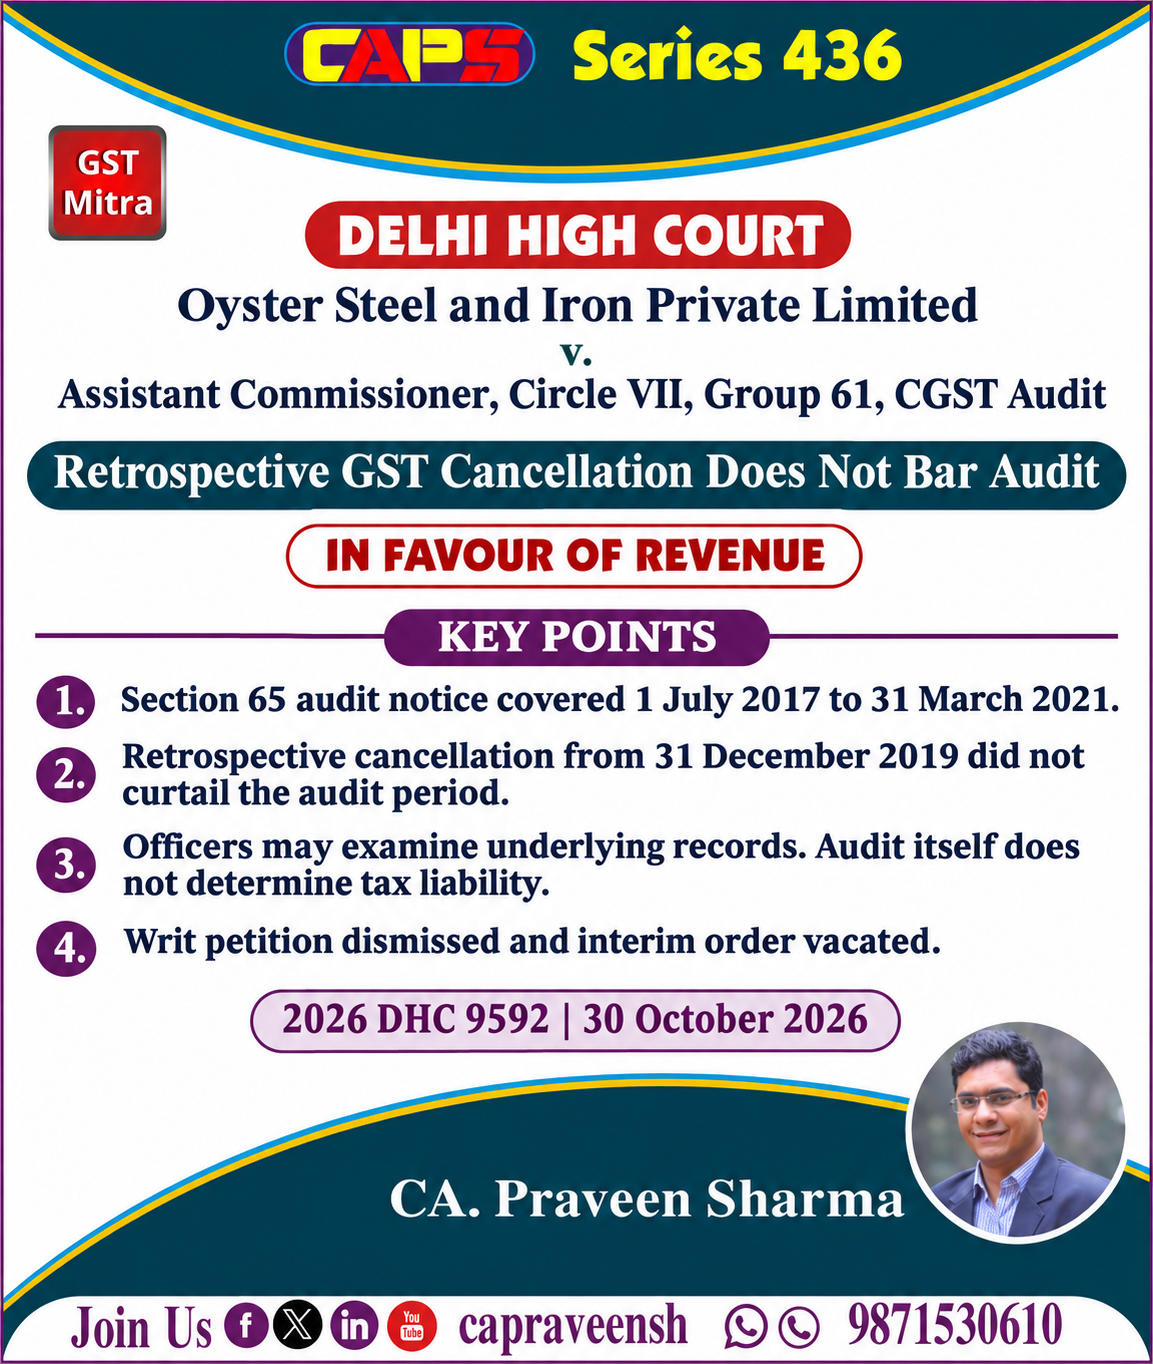
DELHI HIGH COURT IN THE CASE OF Oyster Steel and Iron Private Limited v. Assistant Commissioner, Circle VII, Group 61, CGST Audit
Oyster Steel and Iron Private Limited v. Assistant Commissioner, Circle VII, Group 61, CGST Audit
Outcome: In favour of Revenue.
Cancellation sought: The company applied on 11 January 2020 to cancel its GST registration retrospectively from 31 December 2019, citing business closure.
Audit notice: While cancellation remained pending, the Department issued notice dated 15 September 2022 covering 1 July 2017–31 March 2021.
Taxpayer’s objection: The company argued that retrospective cancellation barred audit under Section 65, particularly for the period after December 2019.
Court’s holding: Subsequent retrospective cancellation does not, by itself, bar audit of records relating to registration previously granted.
Past records remain examinable: Cancellation alters registration’s legal effect but does not erase historical records and conduct.
No presumed tax liability: The ruling neither validates post-cancellation returns nor establishes taxable supplies or liability after December 2019.
Non-disclosure mattered: Failure to disclose the pending audit in earlier cancellation proceedings independently justified refusal of discretionary relief.
Final result: The writ petition was dismissed, the audit notice remained undisturbed, and the interim stay was vacated.
LINK:CA. Praveen Sharma on Linkedin
Best Regards
CA Praveen Sharma
Mob. No. +91-98715 30610
0 Comments: