

GST Update
Desk of CA. Praveen Sharma – 1065 Series (CAPS)
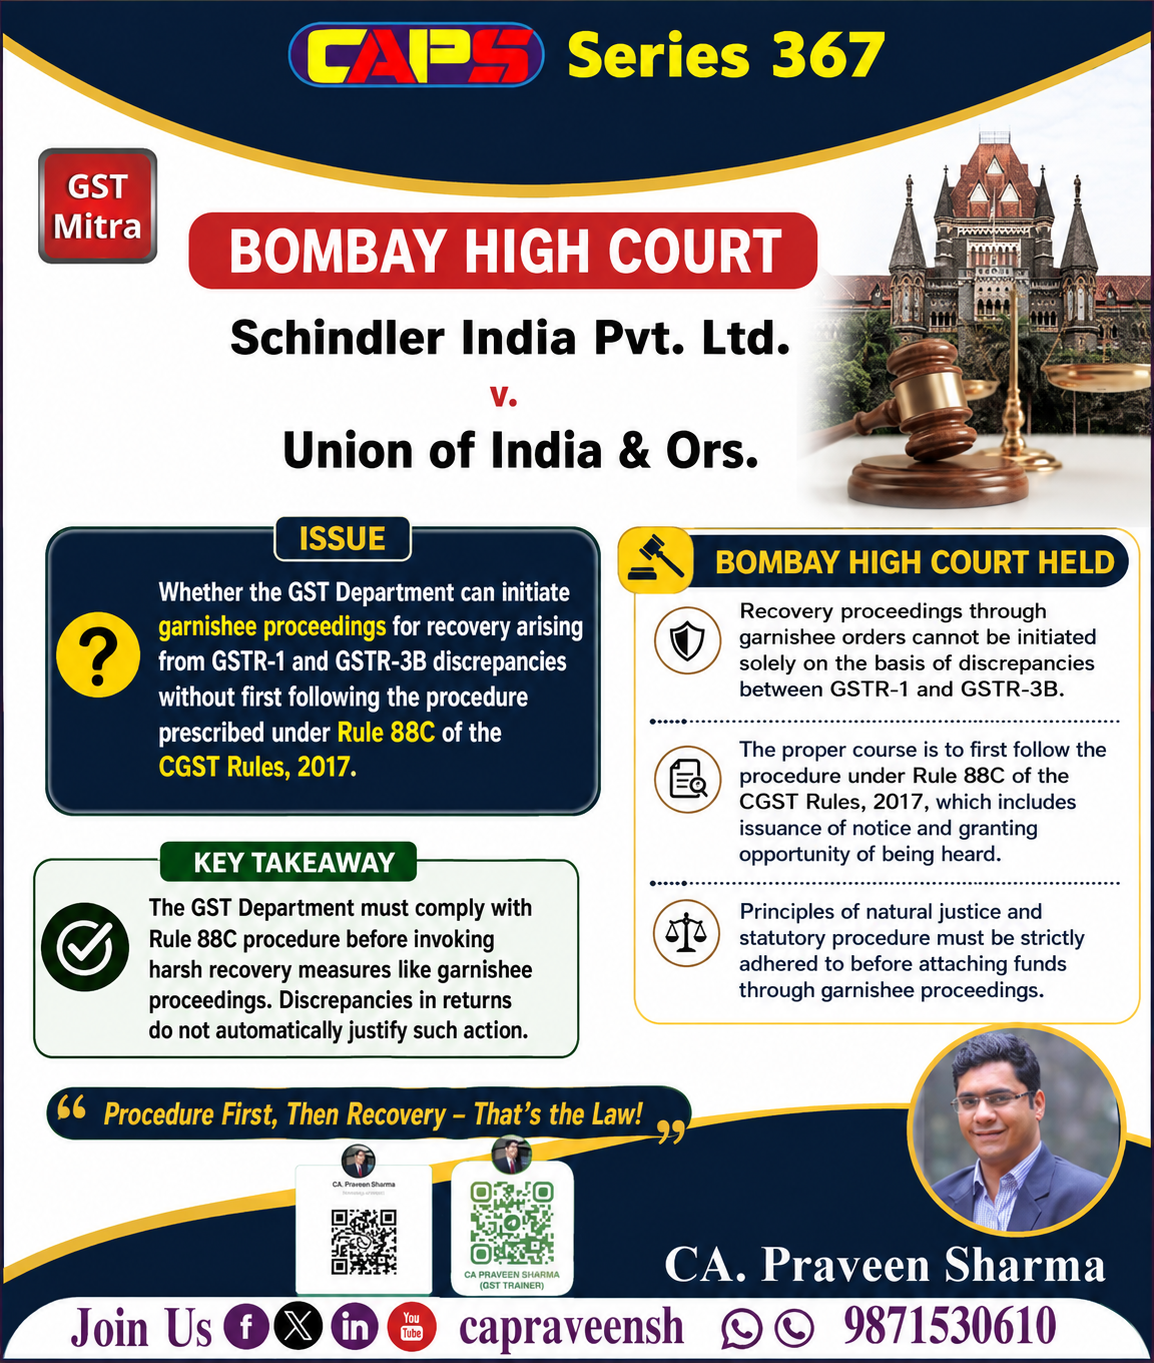
Bombay High Court IN THE CASE OF Schindler India Pvt. Ltd. v. Union of India & Ors.
Issue: Whether the GST Department can initiate garnishee proceedings for recovery arising from GSTR-1 and GSTR-3B discrepancies without first following the procedure prescribed under Rule 88C of the CGST Rules, 2017.
Bombay High Court: Rule 88C Must Be Followed Before GST Recovery
The Bombay High Court in Schindler India Pvt. Ltd. v. Union of India & Ors. dealt with an important issue relating to recovery arising from differences between GSTR-1 and GSTR-3B.
The Court held that the GST Department cannot directly initiate coercive recovery or garnishee proceedings merely because a mismatch exists between the two returns.
Under Rule 88C of the CGST Rules, 2017, the Department must first communicate the discrepancy to the taxpayer through Form GST DRC-01B. The taxpayer must be given an opportunity to either pay the differential tax with applicable interest or provide an explanation for the difference.
Only after following the prescribed procedure can further recovery action be considered in accordance with law.
The Court emphasized that statutory procedure and principles of natural justice cannot be bypassed while taking coercive action against a taxpayer.
Key Takeaway: A GSTR-1 vs. GSTR-3B mismatch by itself cannot justify direct garnishee proceedings. Rule 88C procedure must come first.
LINK: CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: