

GST Update
Desk of CA. Praveen Sharma – 1065 Series (CAPS)
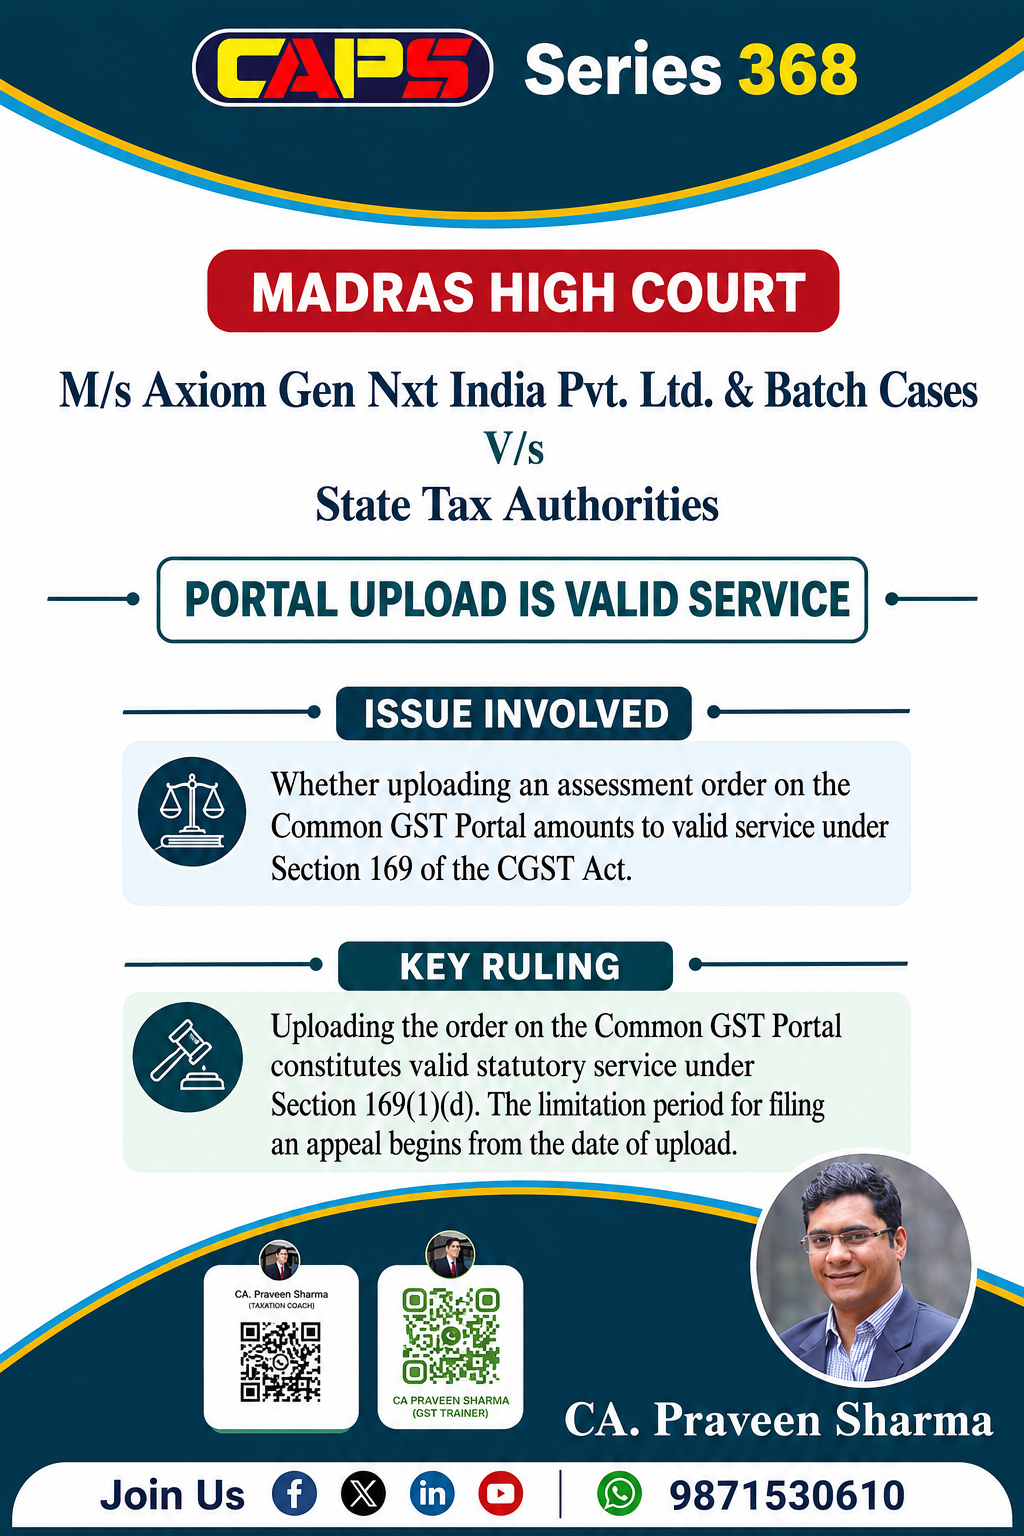
Madras High Court – M/s Axiom Gen Nxt India Pvt. Ltd. & Batch Cases v. State Tax Authorities
Issue: Whether uploading an assessment order on the Common GST Portal amounts to valid service under Section 169 of the CGST Act.
Uploading GST Orders on the Portal Is Valid Service: Madras High Court
The Madras High Court, in M/s Axiom Gen Nxt India Pvt. Ltd. and Batch Cases v. State Tax Authorities, considered whether uploading assessment orders on the Common GST Portal amounts to valid service under Section 169 of the CGST Act.
The taxpayers argued that merely uploading notices and orders on the GST portal should not be treated as proper service. They claimed that the Department should have communicated the orders through some other mode as well.
The High Court rejected this argument. It observed that Section 169(1)(d) specifically permits the service of notices, orders and other GST communications by making them available on the Common Portal. Therefore, once an order is uploaded on the portal, it is treated as validly served upon the registered taxpayer.
The Court further clarified that the time limit for filing an appeal under Section 107 begins from the date on which the order is uploaded on the GST portal. A taxpayer cannot avoid the consequences of delayed filing merely by stating that the portal was not regularly checked.
Although SMS and email alerts may also be sent by the Department, these are only additional forms of intimation and are not compulsory for completing valid service through the portal.
However, the Court advised that where taxpayers repeatedly fail to respond, the authorities should consider using other legally permitted modes of communication as a matter of good administrative practice.
The judgment highlights the importance of regularly checking the GST portal for notices, orders and other official communications. Registered taxpayers should also keep their email address and mobile number updated to avoid missing important proceedings.
LINK:CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: