

GST Update
???? ???????????????? ???????? ????????. ???????????????????????????? ???????????????????????? – ???????????????? ???????????????????????? (????????????????) ????
?? ???????????????????? ???????????????? ???????????????????? — ???????????????????????????????????? ???????????? ????????????????????????
???????????????????????????????????? ???????????????????????? ???????????????? ???????????????????? ????. ????????????????????????????????????????????????????????, ????????????????????-????????, ????????????????
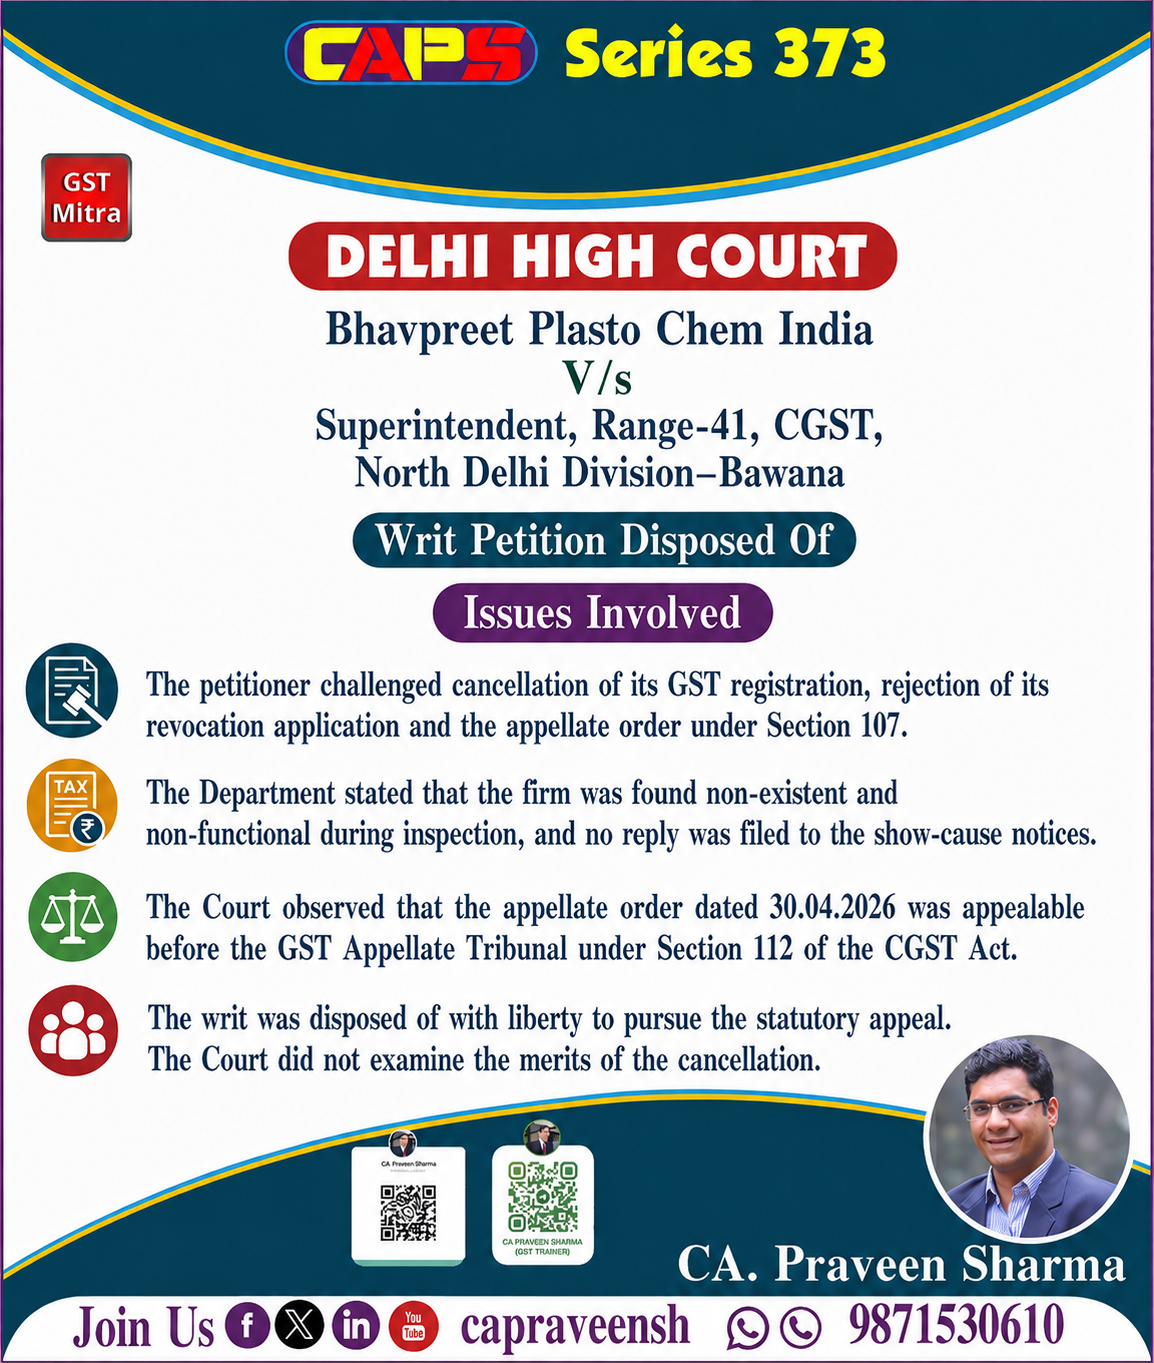
Bhavpreet Plasto Chem India filed a writ petition before the Delhi High Court challenging the cancellation of its GST registration.
The GST Department had inspected the firm’s registered premises. During the inspection, the firm was allegedly found to be non-existent and not operating from the declared place of business.
Based on the inspection report, the Department issued a show-cause notice proposing cancellation of the GST registration. The notice was communicated through the taxpayer’s registered mobile number and email address. However, the taxpayer did not submit any reply or supporting documents.
Consequently, the GST registration was cancelled on 15 October 2025.
The taxpayer then applied for revocation of the cancellation. Before rejecting the application, the Department issued another show-cause notice dated 3 December 2025. The taxpayer again failed to file a reply or provide documents proving that it was carrying on genuine business activities from the registered premises. Therefore, the revocation application was rejected on 6 January 2026.
The taxpayer filed an appeal under Section 107 of the CGST Act, but the Appellate Authority also decided against it on 30 April 2026.
The Delhi High Court observed that the appellate order could be further challenged before the GST Appellate Tribunal under Section 112. Since an effective statutory remedy was available, the Court did not examine the merits of the cancellation.
Accordingly, the writ petition was disposed of, with liberty to the taxpayer to approach the GST Appellate Tribunal.
???? ???????????? ????????????????????????????????:
Taxpayers should respond to every GST notice on time and submit proper documents. A writ petition may not be entertained when an effective statutory appeal is available.
LINK:CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: