

GST Update
Desk of CA. Praveen Sharma – 1085 Series (CAPS)
Gujarat High Court Grants Relief in IGST Refund Matter
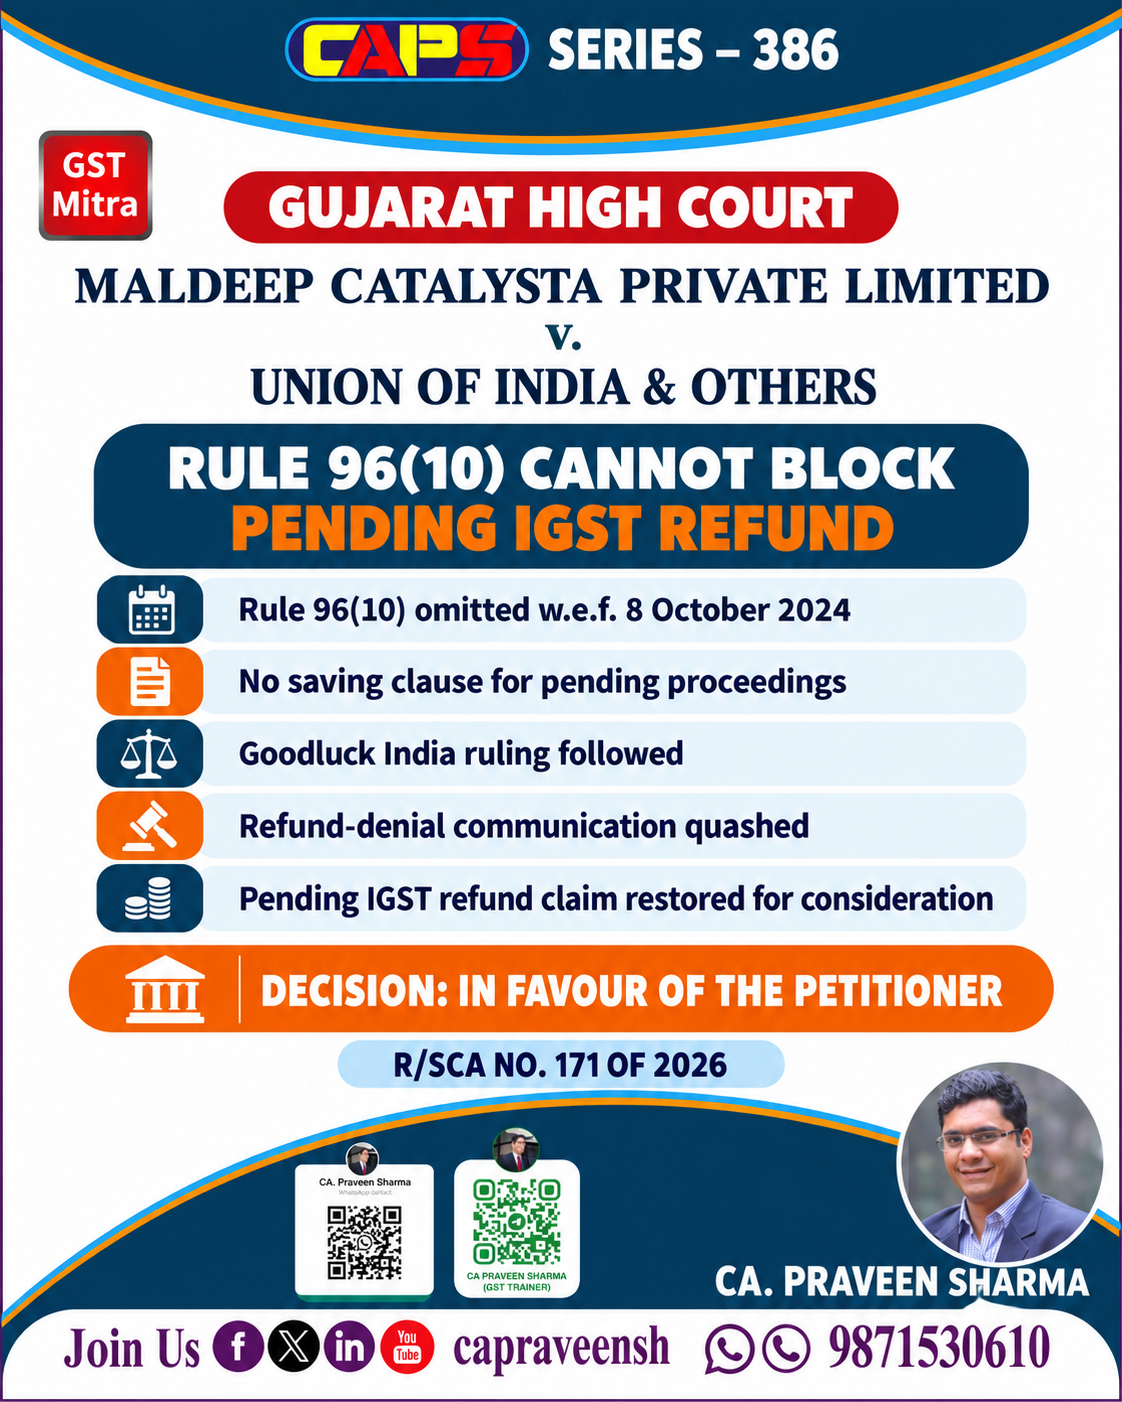
In the case of Maldeep Catalysta Private Limited v. Union of India and Others, the Gujarat High Court granted relief to the petitioner concerning its pending IGST refund on exports.
MldeMldeep Catalysta Private Limited had claimed a refund of IGST paid on exported goods. goods. However, the GST authorities issued a communication dated 8 July 20255 proposing to restrict the refund by applying Rule 96(10) of the CGST Rules.
ST Rules.
Rule 96(10) was omitted with effect from 8 October 2024 2024 through Notification No. 20/2024-Central Tax. The petitioner argued that petitioner argued that once the rule had been omitted, it could not be applied to refund proceedings proceedings that remained pending.
The Court noted that the omission of Rule 96(10) was) was not accompanied by any saving provision preserving its application to pending matters. It also relied upon also relied upon the Supreme Court’s decision in Goodluck India Limited, which recognised that the rule the rule was omitted to remove unnecessary complications faced by exporters.
The Gujarat High Court held that the benefit that the benefit of the omission would also apply to proceedings pending on the date the rule was the rule was removed. Accordingly, it quashed the communication seeking to deny or restrict or restrict the petitioner’s IGST refund.
The writ petition was allowed, and the authorities were required to process the pending refund without applying the omitted Rule 96(10).
Key takeaway:
In the absence of an express saving provision, omitted Rule 96(10) cannot be invoked to deny or restrict or restrict an IGST refund in pending proceedings.
Link: CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: