

GST Update
Desk of CA. Praveen Sharma – 1090 Series (CAPS)
?? Gauhati High Court Upholds Consolidated GST Notice After Search
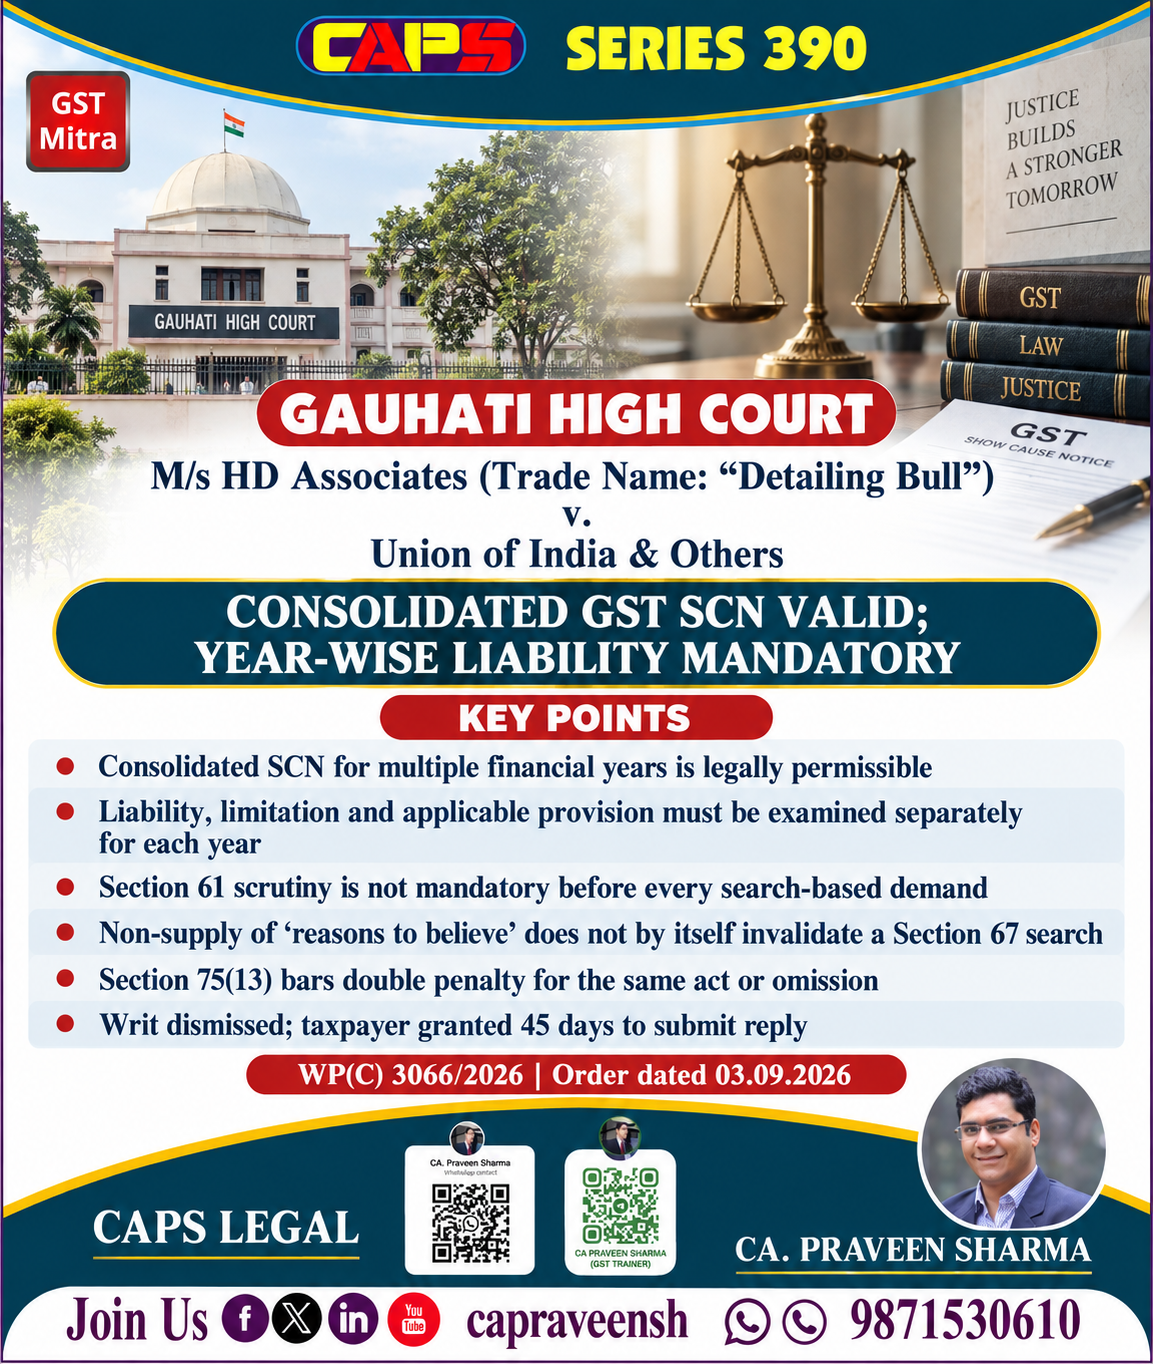
In M/s HD Associates (Trade Name: “Detailing Bull”) v. Union of India & Others, the Gauhati High Court refused to quash a consolidated GST demand-cum-show cause notice issued after a search under Section 67.
The notice covered FY 2021-22 to FY 2024-25 and invoked Sections 74, 74A and 122. The Department alleged suppression of taxable value of approximately ?3.42 crore, involving GST of about ?61.67 lakh.
The petitioner questioned the validity of the search, absence of valid “reasons to believe,” DIN-related defects and failure to conduct scrutiny under Section 61.
The High Court held that non-supply of recorded reasons does not automatically prove that no valid reasons existed. It further clarified that scrutiny of returns under Section 61 and issuance of ASMT-10 are not mandatory where demand proceedings originate from independent search and investigation material.
The Court also held that a single consolidated notice covering multiple financial years is legally permissible. However, liability, limitation and the applicable legal provisions must be examined separately for every financial year. Double penalty for the same act is prohibited under Section 75(13).
Accordingly, the Court declined to interfere with the notice and granted the petitioner 45 days to file a detailed reply.
Key takeaway: Section 61 scrutiny is not a mandatory precondition when GST proceedings arise from a search-based investigation.
LINK:CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: