

GST Update
Desk of CA. Praveen Sharma – 1093 Series (CAPS)
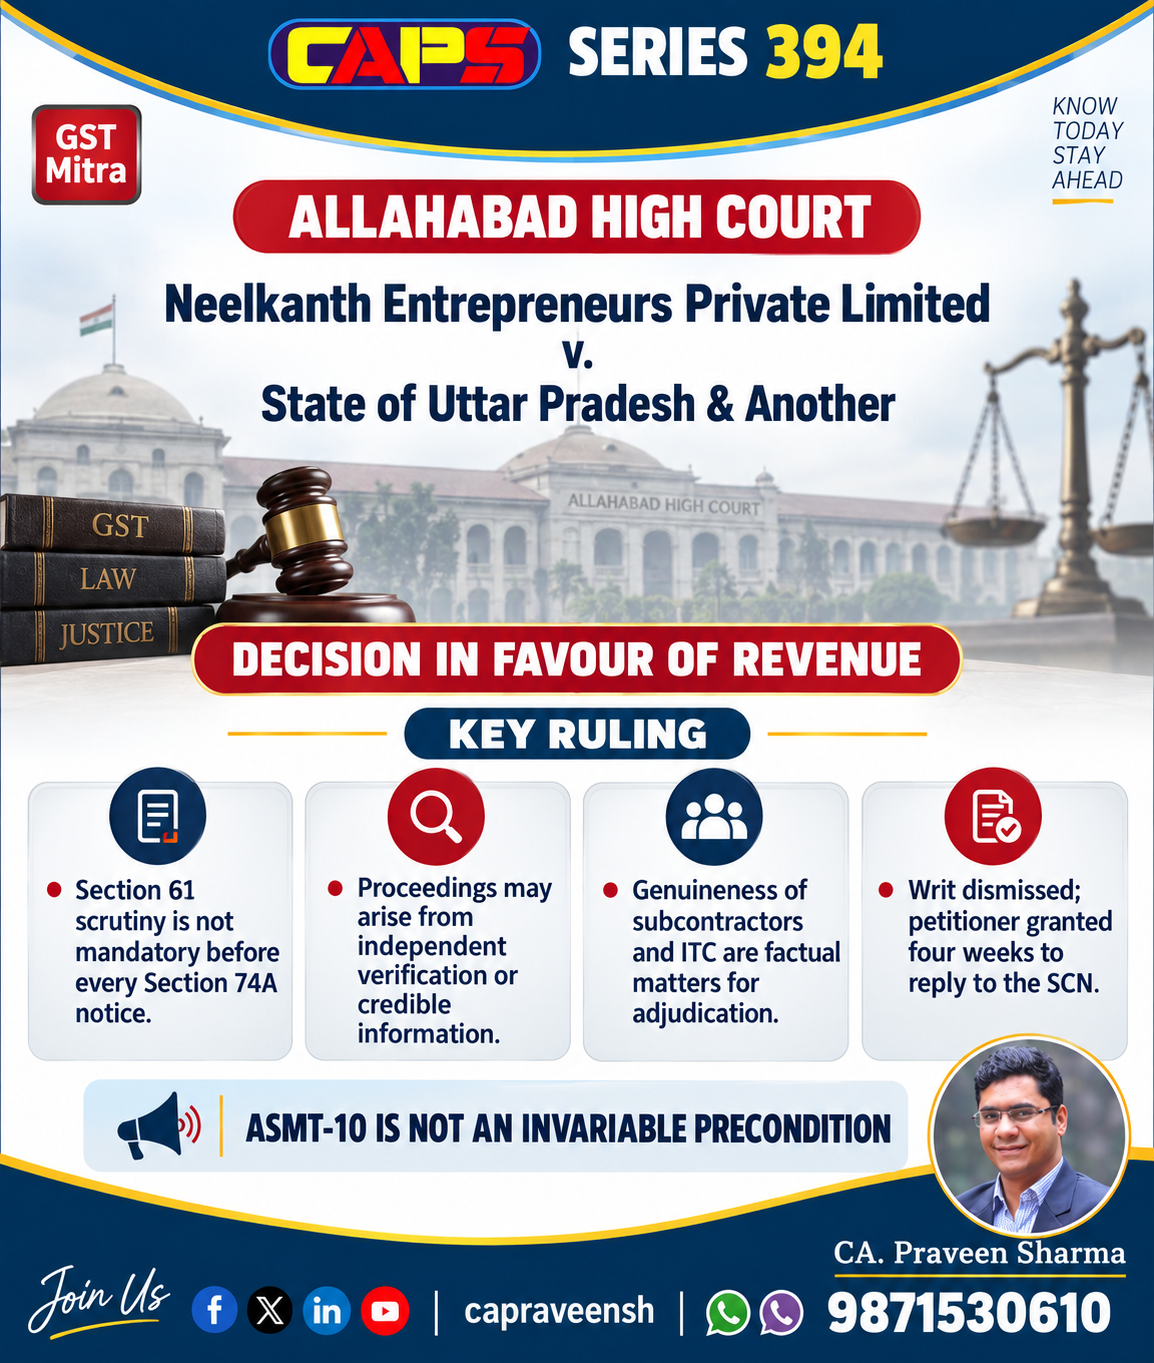
Section 61 Scrutiny Not Mandatory Before Every Section 74A Notice: Allahabad High Court
Neelkanth Entrepreneurs Private Limited v. State of Uttar Pradesh & Another
Decision: In favour of the Revenue
The petitioner, a works-contract service provider, claimed Input Tax Credit on services received from 18 registered subcontractors. Based on independent verification, the GST Department alleged that these subcontractors were bogus or non-existent and issued a show-cause notice under Section 74A(1), proposing denial of ITC along with interest and penalty.
The petitioner challenged the notice, arguing that scrutiny under Section 61 and issuance of Form GST ASMT-10 under Rule 99 were mandatory before initiating proceedings under Section 74A.
The Allahabad High Court rejected this argument. It held that scrutiny under Section 61 is not an invariable precondition for invoking Section 74A. Such proceedings may arise from an audit, inspection, independent verification or other credible information available to the Department.
However, where proceedings are based solely on discrepancies found in returns, compliance with Section 61 and Rule 99 may operate as a mandatory procedural safeguard.
The Court further observed that the genuineness of the subcontractors and the actual execution of work were factual matters requiring examination by the adjudicating authority.
Since the petitioner approached the High Court without submitting a reply to the show-cause notice, the writ petition was dismissed. The Court granted four weeks to file a detailed reply before the proper officer.
Key Takeaway
Section 61 scrutiny and issuance of Form GST ASMT-10 are not mandatory before every notice under Section 74A, particularly where the proceedings are based on independent verification. Factual disputes concerning bogus suppliers and fraudulent ITC should ordinarily be raised before the adjudicating authority.
LINK: CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: