

GST Update
Desk of CA. Praveen Sharma – 1100 Series (CAPS)
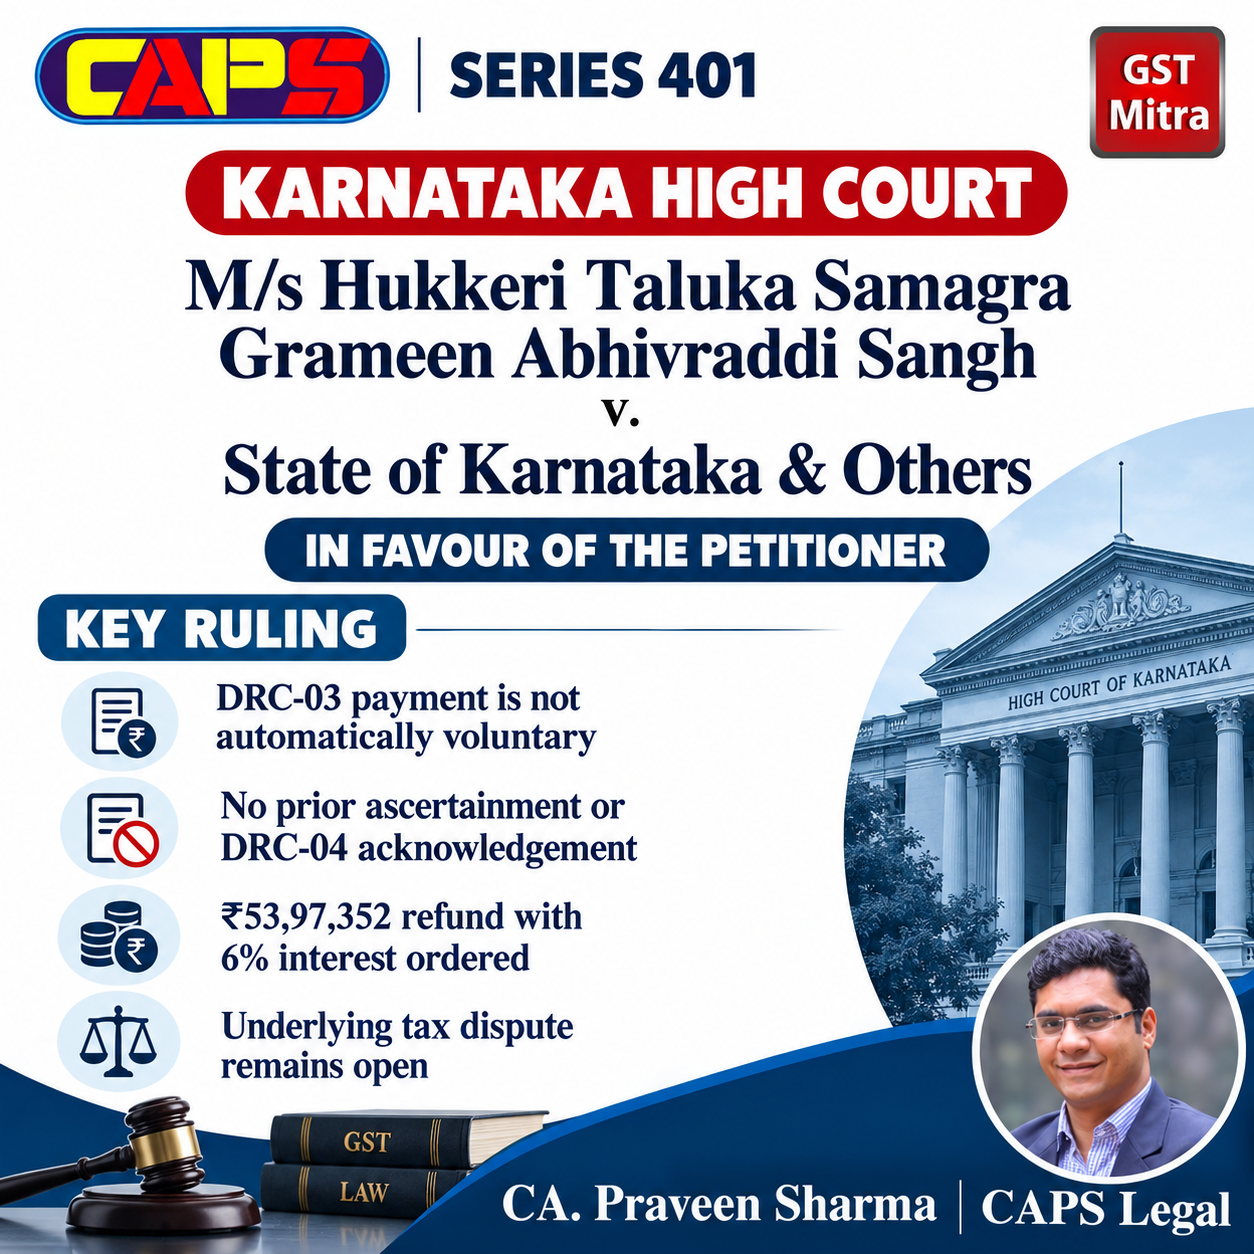
Karnataka High Court: M/s Hukkeri Taluka Samagra Grameen Abhivraddi Sangh v. State of Karnataka & Others
In favour of the petitioner
The petitioner: M/s Hukkeri Taluka Samagra Grameen Abhivraddi Sangh provided manpower-supply services to government departments and public authorities.
Investigation began: GST officers inspected its premises on 20 January 2024 following an alleged discrepancy between GSTR-3B and GSTR-7 records.
Payments through DRC-03: The petitioner paid ?20,97,352 and ?15 lakh on 27 March 2024, followed by ?18 lakh on 14 May 2024. It maintained that these payments were made under pressure.
Core question: The Court examined whether filing Form GST DRC-03 made the payments voluntary under Section 73(5) or 74(5), as the Department contended.
No established ascertainment: The Department showed no material demonstrating that the petitioner had calculated and admitted the liability, or that the proper officer had ascertained the amount before payment.
No DRC-04 acknowledgment: Although Rule 142(2) requires acknowledgment in Form GST DRC-04 for a payment made in DRC-03 under the cited provisions, none was issued.
Interest and penalty were absent: The Department relied on Section 74(5), yet the DRC-03 forms showed nil interest and nil penalty. The Court treated this as another circumstance against the claim of a voluntary payment under that provision.
Later proceedings did not establish voluntariness: The Court held that proceedings under Section 79 could not, by themselves, show that the earlier payments had been voluntary.
Refund ordered: The Court allowed the writ petition, quashed the appellate orders rejecting the refund claims, and directed a refund of ?53,97,352 with 6% annual interest from the dates of payment until refund.
Tax merits remain open: The ruling decides the treatment of the payments and refund. The Court expressly left the parties’ competing positions on the underlying tax liability open for the separate show cause and adjudication proceedings.
LINK:CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: