

GST Update
Desk of CA. Praveen Sharma – 1103 Series (CAPS)
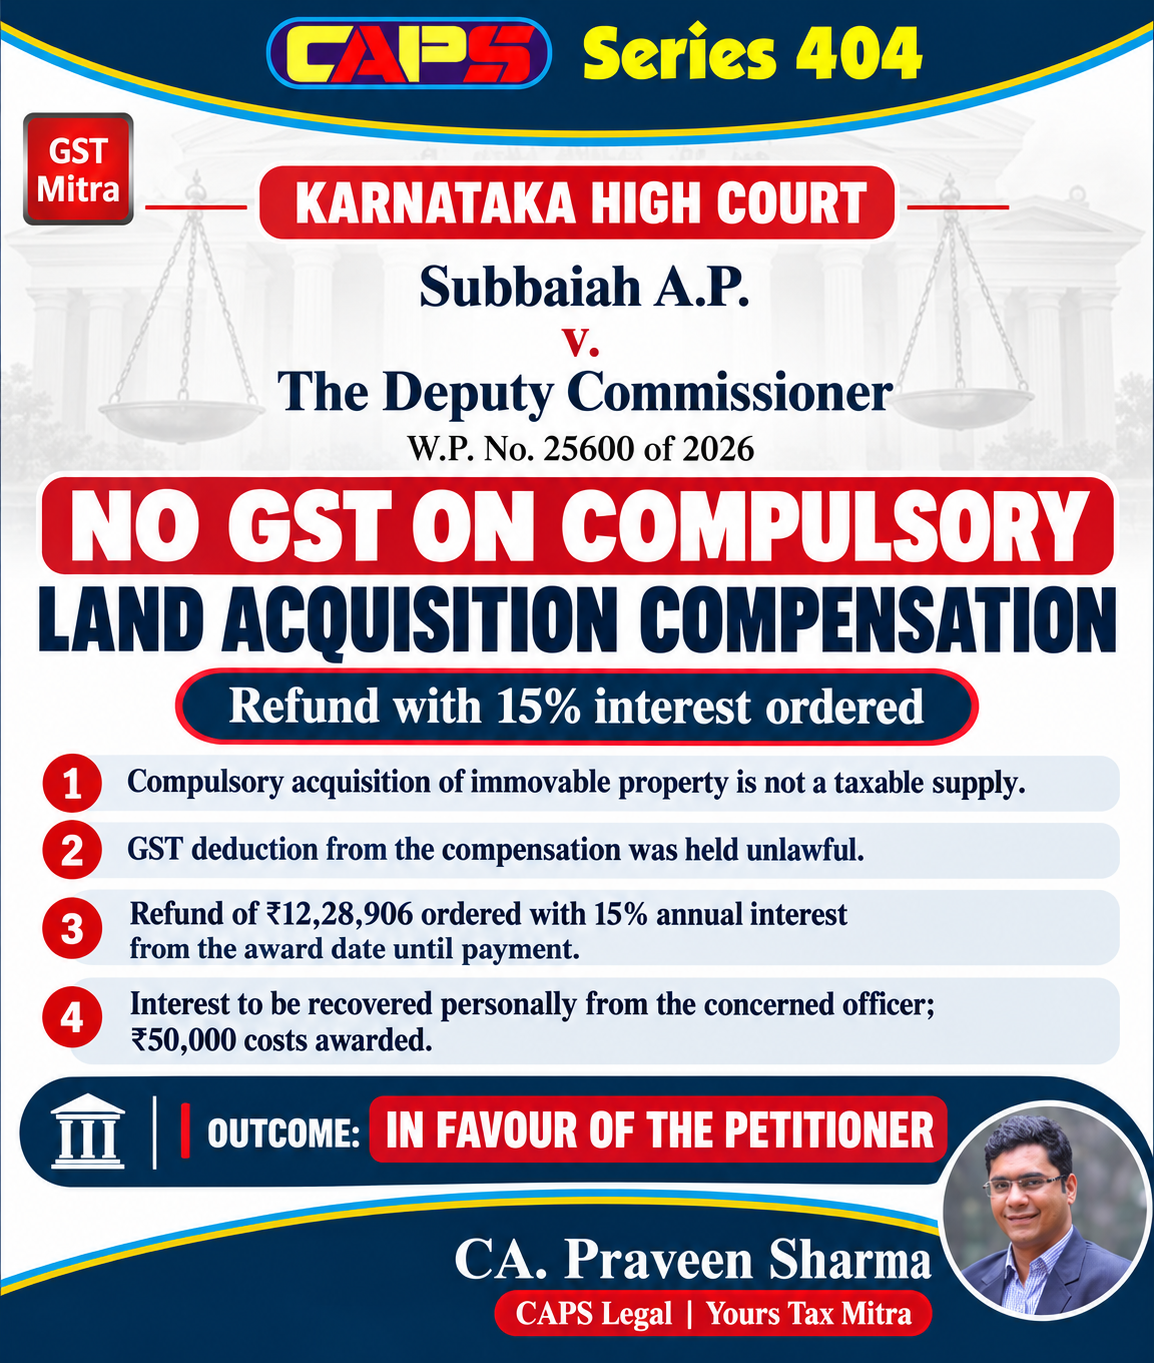
KARNATAKA HIGH COURT IN THE CASE OF Subbaiah A.P. v. The Deputy Commissioner
No GST on Compulsory Land Acquisition Compensation: Refund With 15% Interest Ordered
Outcome: In favour of petitioner
The petitioners are individual landowners, rather than a company.
Background: Four landowners’ house property was compulsorily acquired for widening the Mysuru–Madikeri Highway.
GST deduction: Authorities deducted ?12,28,906 as GST from their compensation.
Challenge: The landowners contested the deduction, asserting that they had supplied neither goods nor services.
No taxable supply: The Court held that compulsory acquisition under the State’s statutory powers does not constitute a GST supply.
Immovable property: The acquired land and attached structure were immovable property.
Structure argument rejected: Authorities identified no GST provision authorising taxation of the acquired structure.
Excess of authority: The Court held that deducting GST from the compensation exceeded the respondents’ powers.
Refund ordered: The award notice was quashed to the extent of the GST deduction, and ?12,28,906 was ordered refunded.
Personal recovery of interest: 15% annual interest, from the award date until payment, was directed to be recovered personally from the concerned officer.
Litigation costs: The Court also ordered ?50,000 as costs for expenses incurred in pursuing the petition.
LINK:CA. Praveen Sharma on Linkedin
Regards
CAPS
0 Comments: