

GST Update
Desk of CA. Praveen Sharma – 1114 Series (CAPS)
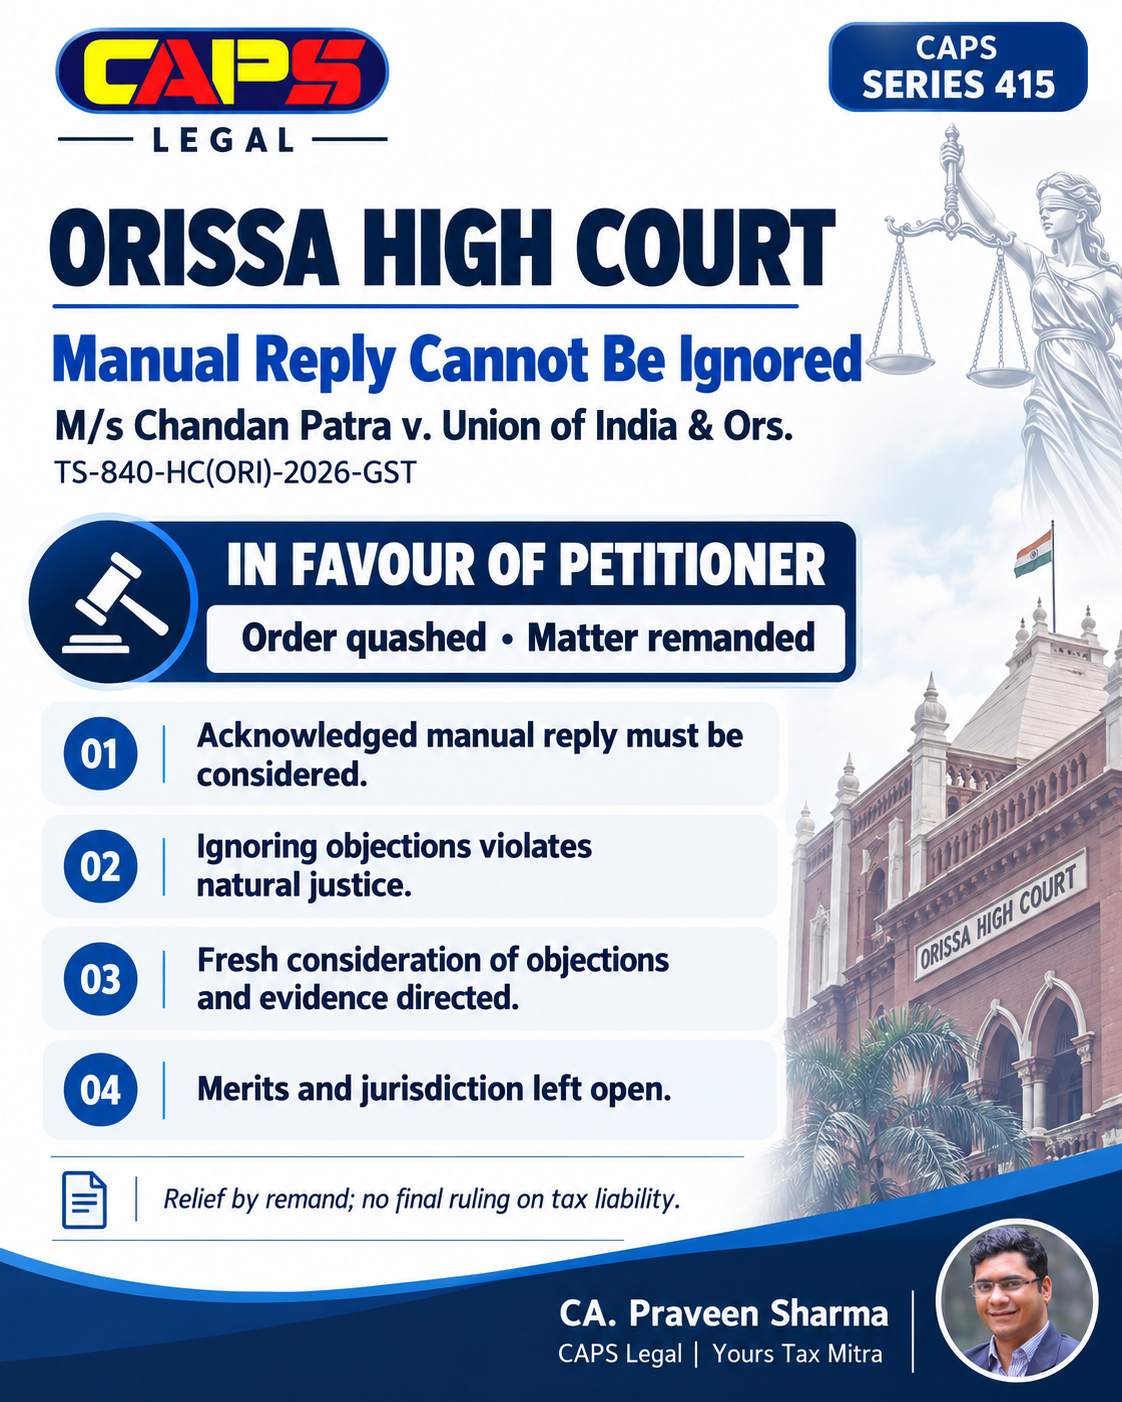
Orissa High Court IN THE CASE OF M/s Chandan Patra v. Union of India & Ors.
Citation: TS-840-HC(ORI)-2026-GST
Dispute: M/s Chandan Patra challenged a GST adjudication order passed without considering its written defence.
Manual reply: The petitioner attended the hearing on 27 January 2026 and submitted a detailed reply physically.
Acknowledged receipt: The Superintendent received and signed the reply, establishing its presence on record.
Premature order: Despite granting time until 13 February 2026 for documents, the authority passed the order on 4 February 2026.
Incorrect premise: The order proceeded as though the petitioner had neither appeared nor submitted a reply.
Statutory duty: Section 74(9) requires consideration of the taxpayer’s representation before determining liability.
Filing mode: Reading Rule 142(4) with Section 74(9), the Court held that an acknowledged manual reply cannot be ignored merely for non-uploading.
Natural justice: Procedural requirements cannot become a technical barrier depriving taxpayers of their right to defend.
Outcome: In favour of M/s Chandan Patra. The order was quashed and the matter remanded for fresh consideration of objections and evidence.
LINK:CA. Praveen Sharma on Linkedin
Best Regards,
CA Praveen Sharma
Mob. No. +91-98715 30610
0 Comments: