

GST Update
Desk of CA. Praveen Sharma – 1123 Series (CAPS)
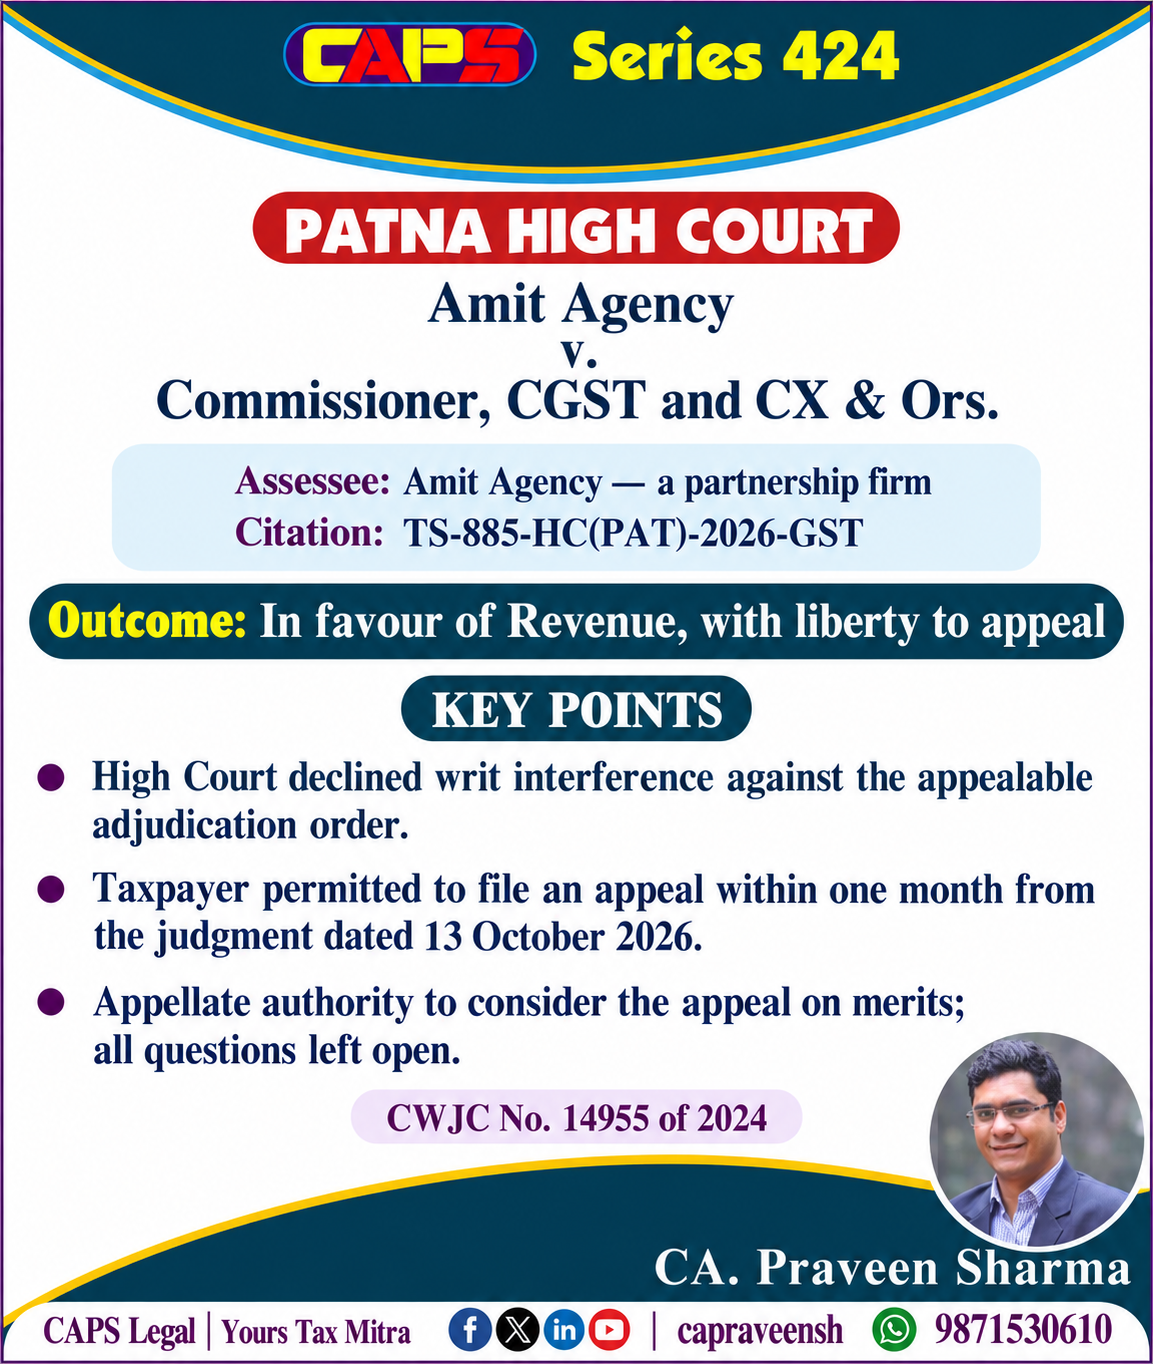
Patna High Court IN THE CASE OF Amit Agency v. Commissioner, CGST and CX & Ors.
Assessee: Amit Agency—a partnership firm
Citation: TS-885-HC(PAT)-2026-GST
Outcome: In favour of Respondents—Revenue, with liberty to appeal.
Audit dispute: The proceedings covered FYs 2017–18 to 2019–20.
Uncontested report: The Court noted no demonstrated challenge to the final audit report.
Specific allegations: The SCN detailed unpaid GST, short payments, RCM liabilities and late fees.
Section 74 sustained: The Court found sufficient grounds to reject the jurisdictional challenge on these facts.
Bona fide defaults distinguished: Mere non-payment for bona fide reasons cannot automatically attract extended limitation.
Officer’s satisfaction: Invocation required satisfaction regarding wilful suppression or concealment.
No jurisdictional error: The SCN showed application of mind.
Statutory appeal preferred: The Court declined writ interference and allowed one month to appeal.
Merits remained open: The appellate authority must independently examine the adjudication order; observations were confined to the SCN challenge.
LINK:CA. Praveen Sharma on Linkedin
Best Regards,
CA Praveen Sharma
Mob. No. +91-98715 30610
0 Comments: